Let me ask you something straight up: If you could give your military clients 2-3 times more money in their pocket while keeping 100% of your commission, wouldn't you want to know about it?
Of course you would. So why aren't you using it?
Here's the uncomfortable truth: Most real estate agents are settling for programs that shortchange both themselves and the military families they serve. And frankly, our heroes deserve better than your leftovers.
The Program Everyone Knows (But Shouldn't Be Using)
You've heard of Homes for Heroes. It's everywhere. Military families get a rebate, and you: the agent: give up 30% of your hard-earned commission to make it happen.
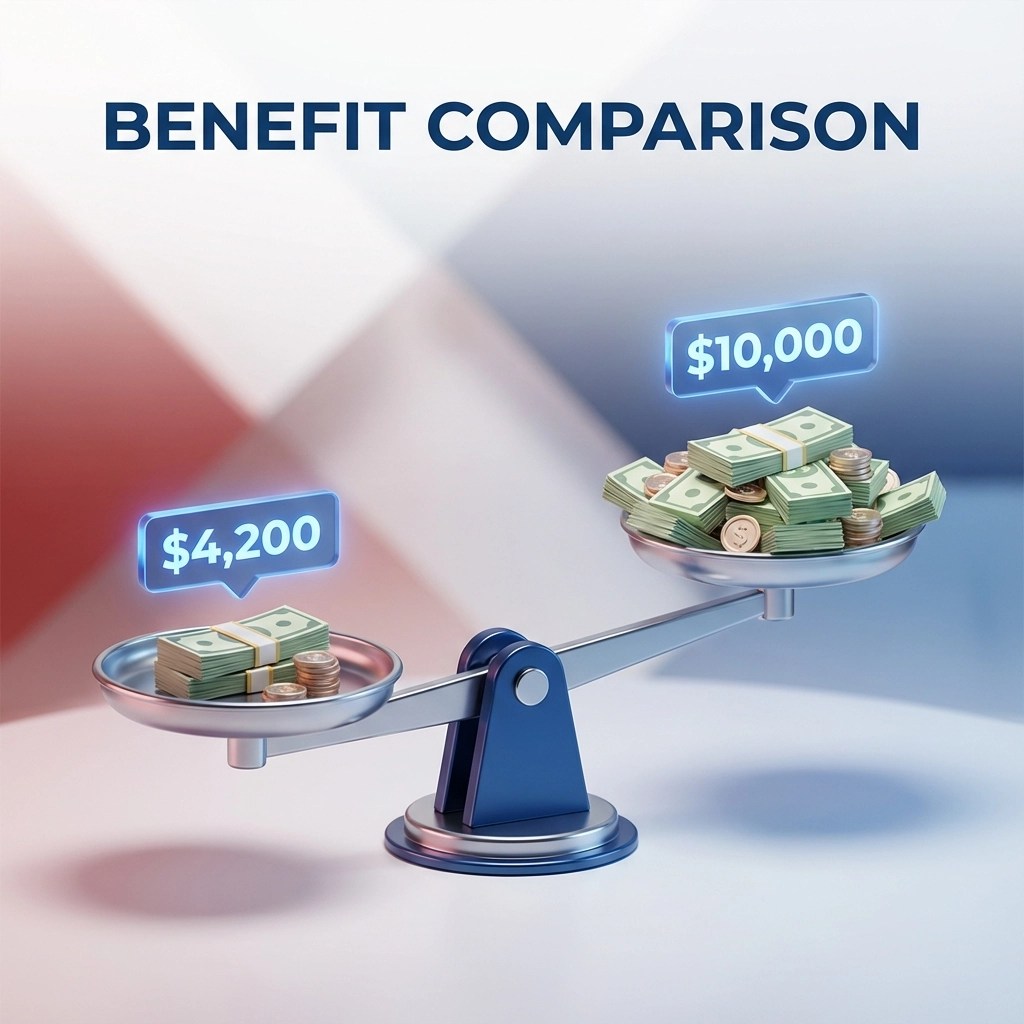
For a military family buying a $500,000 home with a VA loan, Homes for Heroes typically provides around $4,200 in benefits. Not bad, right?
But here's where it gets interesting: You just gave up 30% of your commission to make that happen. On a $500,000 home with a 3% commission split, that's roughly $4,500 out of your pocket.
So let me get this straight: you gave up more money than the military family even received?
That doesn't sound like a win-win. That sounds like you got played.

The Program You Should Be Using (But Probably Aren't)
Meet Operation T.A.G. and the Hometown Hero Credit: a non-profit program that's about to make you wonder why you've been doing things the hard way.
Same military family. Same $500,000 home. Same VA loan with zero down payment.
But here's where everything changes:
Hometown Hero Credit provides 2% of the loan amount, up to $21,000. For our $500,000 example, that's $10,000 straight to the military family: more than double what Homes for Heroes offers.
And your commission? You keep every single penny.
Zero percent commission sharing. One hundred percent of your money stays with you.
Let me break this down in terms even a rookie agent can understand:
- Homes for Heroes: Military family gets $4,200, agent loses $4,500
- Hometown Hero Credit: Military family gets $10,000, agent loses $0
Which scenario makes you look like a hero to your client? Which one makes better business sense for you?
But Wait: It Gets Even Better
That $10,000 isn't just sitting there looking pretty. Your military clients can use the Hometown Hero Credit to:
- Pay closing costs
- Buy down their interest rate
- Cover real estate agent fees
- Pay down debt to help with VA loan qualification
The only thing they can't use it for is a down payment: but with a VA loan, they don't need one anyway.
This is real money solving real problems for families who've served our country. And you get to be the agent who made it happen while keeping your full commission.

So Why Isn't Every Agent Using This?
Good question. Here's my theory:
Most agents don't know about it. The big programs spend millions on marketing. We're a non-profit focused on results, not billboards.
Some agents are afraid of change. They're comfortable with the devil they know, even if that devil is taking 30% of their commission.
Others think "if it sounds too good to be true…" But here's the thing: this isn't too good to be true. It's just better than what you're used to.
And some agents simply don't care enough to research better options for their military clients. If that's you, this blog isn't going to change your mind. But your military families deserve an agent who gives a damn.
The Numbers Don't Lie
Let's run through this one more time with crystal clarity:
Military family buying a $500,000 home with VA loan (no down payment):
Homes for Heroes Program:
- Military family benefit: ~$4,200
- Agent commission loss: ~$4,500 (30% of $15,000 commission)
- Agent net benefit: -$300 (you actually LOST money helping your client)
Operation T.A.G./Hometown Hero Credit:
- Military family benefit: $10,000 (2% of $500,000 loan)
- Agent commission loss: $0
- Agent net benefit: +$15,000 (your full commission)
The military family gets $5,800 more. You keep $4,500 more. Everyone wins except the programs that have been taking advantage of both of you.
Your Military Families Are Watching
Here's what really matters: Your military clients trust you to find them the best deal possible. When you use a program that gives them less money while costing you more, you're failing that trust.
They don't know there's a better option because you're supposed to be the expert. They're counting on you to know about programs like Hometown Hero Credit.
When you don't, you're not just leaving money on the table: you're leaving it in someone else's pocket.
It's Time to Step Up
Every day you're not using Hometown Hero Credit is another day you're shortchanging military families and yourself. These heroes put their lives on the line for our freedom. The least you can do is put in the effort to find them the best homebuying benefits available.
Stop settling for programs that treat you like a charity case. Stop accepting that you have to lose money to help military families save money.
There's a better way. Use it.
Ready to become a Hometown Hero Credit partner? Visit HometownHeroCredit.com and join the agents who are actually making a difference: for their military families and their own bottom line.
Because at the end of the day, shouldn't helping our heroes be profitable for everyone involved?
Brett Stacy
National Director & Founder of Hometown Hero Credit
A program of Operation T.A.G. (Tangible Act of Gratitude)
501(c)(3) non-profit project of HDCF
Phone: 760-456-8748
Website: www.HometownHeroCredit.com
Blog: www.HometownHeroCredit.blog

Leave a Reply